how-to
Can You Finance a Real Estate Auction Purchase?
Editorial Team 12 min read
Quick Summary
Yes, but it is harder than a typical home loan. Auction terms often require full payment within 30 to 45 days and sell properties as-is, so buyers commonly use short-term loans like bridge or hard money loans. Line up auction purchase financing before you bid, since missing the deadline can cost you your deposit.
- Most auction properties are sold as-is, with no inspection or appraisal contingency.
- Many auctions require full payment within 30 to 45 days, which is often too short for a conventional mortgage.
- Bridge loans typically have terms of six months to two years.
- Hard money loans are underwritten on the property's as-is value, repair budget, and after-repair value.
- Have a locked-in exit, such as a refinance pre-approval or sale plan, before taking any short-term loan.
Table of Contents
- How Real Estate Auctions Work and Why Financing Is Harder
- Can a Conventional Mortgage Be Used to Buy at Auction?
- Auction Bridge Loans for Short-Term Purchase Funding
- Hard Money Loans for Auction Property Purchases
- How to Buy a House at Auction Without Cash
- Building an Auction-Ready Financing Timeline
- Your Next Step: Get Pre-Qualified Before the Next Auction
- Frequently Asked Questions
How Real Estate Auctions Work and Why Financing Is Harder
Last Updated: November 5, 2026
Buying a property at auction can move fast. The gavel falls, the winning bidder signs, and the deal is done in a matter of days. That speed is exactly why auction purchase financing is harder to arrange than a typical home loan.
A real estate auction is a public sale where the property goes to the highest bidder (How does foreclosure work?).
Auction properties are often sold as-is, and financing may be restricted. That combination of short deadlines and limited financing is what makes auction purchases different.
As-Is Sales and Limited Contingencies
Most auction properties are sold as-is. You generally cannot ask the seller for repairs or walk away because of a problem you find after the sale.
- No inspection contingency: Many auctions do not let you back out if the inspection shows damage.
- No appraisal contingency: You must pay even if the property appraises lower than your bid.
- Limited access: Some properties cannot be inspected inside before bidding.
Watch out: If you cannot get a loan in time, you may lose your deposit. Line up your financing before you bid.
Can a Conventional Mortgage Be Used to Buy at Auction?
Sometimes, but it is often difficult. A conventional mortgage usually requires an appraisal, a clear title, and a closing timeline of 30 days or more.
Lenders also tend to be cautious about properties that need major repairs or have unclear title.
Before you bid, ask the auctioneer two questions: how long you have to close, and whether the sale allows financing contingencies. If the answer to either is "no," a conventional mortgage is probably not the right tool.
Auction Bridge Loans for Short-Term Purchase Funding
An auction bridge loan is a short-term loan that covers the purchase while you arrange longer-term financing or sell the property. Bridge loans are built for speed and usually have terms of six months to two years. Read how bridge loans work, including typical terms, costs, and exit strategy.
Here is how the math often works. Suppose you win a property at $150,000 and need to close in 30 days. A bridge loan might cover most of the purchase price, while you finance repairs and then refinance or sell.
- Typical use: Buy now, fix up, then refinance into a long-term loan.
- Typical cost: Interest rates and fees vary by lender and borrower profile. Contact Biscayne Lending for current terms.
- Key risk: You must have a clear exit plan. If you cannot refinance or sell, the loan comes due.
The exit strategy matters more than the rate. A bridge loan with a clear path to repayment is a tool. Short-term funding to close now and refinance or sell later lays out the options. Without that path, it becomes a problem.
Hard Money Loans for Auction Property Purchases
Hard money loans are short-term, asset-based loans from private lenders. Instead of underwriting your income or credit score the way a bank does, the lender underwrites the deal: the property's as-is value, the repair budget, the after-repair value (ARV), and your exit plan. That is why hard money is the workhorse of auction financing, it can be approved and funded inside the 30- to 45-day window most auction terms impose, and it does not require the property to be move-in ready or to pass a government-backed appraisal.
How the loan is actually structured
Most hard money auction loans follow a common pattern. Lenders typically fund a percentage of the purchase price or the as-is value, with loan-to-value terms that vary by lender and deal. The purchase and the rehab are often combined into a single loan with a holdback: the acquisition cost is funded at closing, and repair funds are released in draws as work is completed and inspected.
- Term: typically 6 to 24 months, interest-only during the term, with a balloon at maturity.
- Rate and points: hard money is generally priced above conventional financing. Pricing varies widely by lender, leverage, and borrower experience; contact Biscayne Lending for current terms.
- Fees to budget for: origination points, a valuation or appraisal fee, title and escrow costs, document and processing fees, and often a draw inspection fee per rehab release.
- Prepayment: most hard money loans have no prepayment penalty, which matters because the goal is usually to refinance or sell quickly.
A worked cost example
Carrying costs for a hard money loan include interest, origination points, and closing fees. Build these into your maximum bid before you win the property, not after.
Eligibility and property condition
Private lenders are often more flexible than banks on property condition, but they typically require strong collateral and a clear exit. Expect the lender to require clear title or a title policy it can insure, evidence of insurance, and a credible exit (a signed sale contract, a refinance pre-approval, or a documented ARV from comparable sales). Properties with unresolved liens, code violations, or contested occupancy can stall approval even at a private lender.
Where hard money fits against the alternatives
Compared with a conventional mortgage, hard money is generally faster and more tolerant of property condition, but it costs more and requires an exit.
Hard money loans can help you act quickly when an auction deadline is close. Contact Biscayne Lending to discuss the property, the rehab scope, and your exit.
The article's key terms and figures for hard money auction loans are summarised below.
| Feature | Typical detail | Note |
|---|---|---|
| Term | 6 to 24 months | Interest-only, with a balloon at maturity |
| Funding basis | As-is value and rehab budget | Lender underwrites the deal, not income |
| Repair funds | Released in draws | Released as work is completed and inspected |
| Prepayment | Usually no penalty | Matters when refinancing or selling quickly |
| Exit requirement | Refinance pre-approval or sale | Must be locked in before the loan |
| Timeline fit | Inside 30 to 45 day window | Fits most auction closing terms |
How to Buy a House at Auction Without Cash
You do not need all cash to buy at auction, but you do need a plan to fund the purchase within the deadline. Most successful buyers combine several steps.
- Research the property early. Check title, liens, taxes, and condition before auction day.
- Get pre-qualified. Talk to lenders before you bid so you know your maximum budget.
- Set a maximum bid. Include closing costs, repairs, and holding costs in your number.
- Arrange funding in advance. Have a loan commitment ready for the amount you plan to bid.
- Keep a backup plan. If financing falls through, know where you can get short-term funds.
For buyers who plan to renovate before selling or refinancing, fix-and-flip financing is designed for this use.
Building an Auction-Ready Financing Timeline
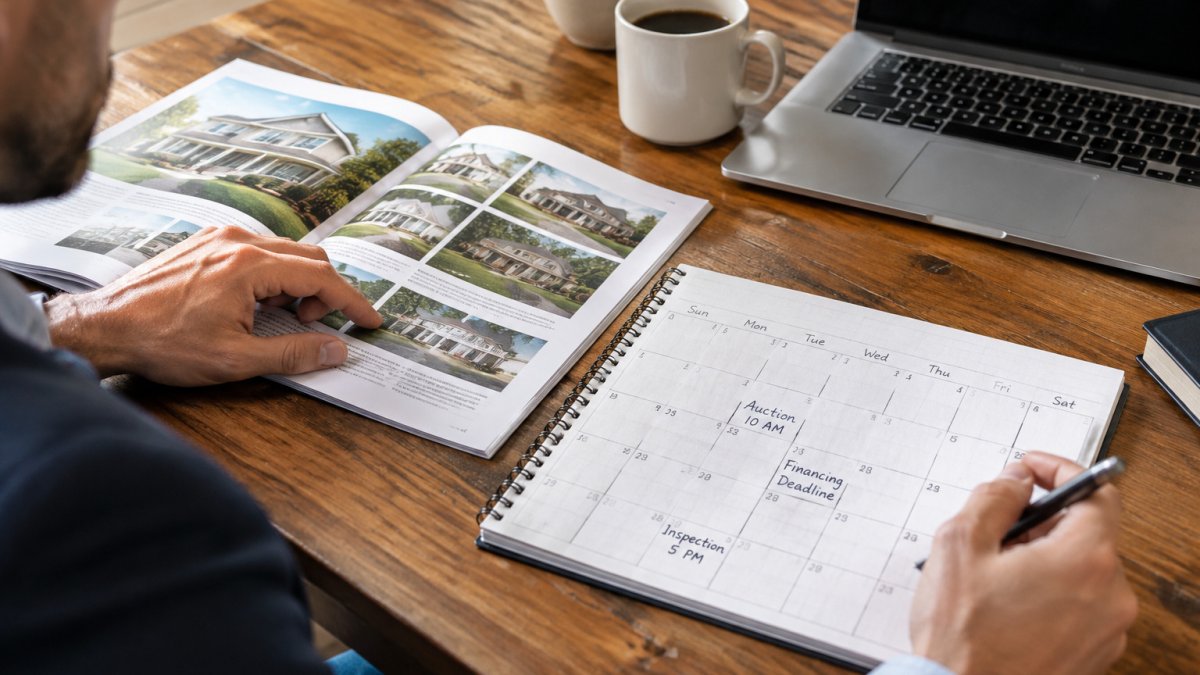
Auction deadlines are unforgiving, and the financing calendar has to run backward from the closing date in the terms of sale, not forward from the day you decide to bid. The single most useful thing you can do is read the auction terms first, write down the deposit amount, the deposit due date, and the completion deadline, and then build every financing step backward from those three dates. Most auction contracts give you 30 to 45 days to close, and the deposit is usually due on the day of sale.
The backward calendar
- Before you register to bid (as early as possible): Pull title, check liens and tax status, confirm occupancy and access, and get a preliminary loan approval sized to your maximum bid. Confirm whether the auction terms permit a financing contingency, most do not.
- One to two weeks before the auction: Lock in your funding source and confirm the amount you can access. If you are using hard money or a bridge loan, get a term sheet with the rate, points, leverage, and draw schedule in writing. Confirm your deposit funds are liquid and available on auction day.
- Auction day: Bid only within your approved maximum. Pay the deposit as required by the terms, usually a percentage of the bid or a fixed amount, due same day. Get a receipt and a copy of the signed contract.
- Within 48 hours of winning: Submit the full loan application and documents, order the valuation or appraisal, and open title and escrow. Confirm the lender's closing timeline against the contract deadline in writing.
- Mid-closing: Clear title exceptions, confirm insurance, and schedule any rehab draws. If the lender needs an inspection or a title cure, build in extra days, these are the steps that slip.
- Closing deadline: Confirm funds are wired and the title company has everything it needs. Do not assume the lender's 'target' closing date matches your contract date.
- After closing (the exit calendar): Start the refinance or sale process immediately. Most hard money and bridge loans are interest-only with a balloon, so the exit is a scheduled event, not an afterthought.
The fallback plan
Even a well-built calendar can break. The two failure points are a lender that cannot fund by the contract deadline and an exit loan that is not available when the balloon comes due.
- If purchase financing stalls: Know your backup source in advance, a second hard money lender, a private investor, or liquid reserves, and confirm the auction terms on extensions and penalties. Many contracts allow a short extension for a fee; some do not.
- If the exit refinance is delayed: Ask your hard money lender about extension terms and cost before closing, and keep a reserve for carrying costs during the extension. A refinance that is 'almost approved' is not an exit.
- If you cannot close at all: You may lose the deposit and face additional remedies under the contract. That is why the deposit should be money you can afford to lose, and why the financing should be committed before the gavel falls.
Watch out: The most common timeline failure is treating the lender's target closing date as the contract deadline.
Missing a step can cost you the deposit. Build in extra time for each stage, especially if the lender needs a title report or property inspection.
Your Next Step: Get Pre-Qualified Before the Next Auction
Auction deals reward buyers who prepare early. Financing is the piece most buyers underestimate, and it is the piece that decides whether you keep the property. Before you bid, confirm what you can borrow, how fast it can close, and what your exit looks like.
Biscayne Lending connects investors with private, institutional, and specialty capital sources through a single application, which can help you move quickly when a deadline is close.
Frequently Asked Questions
Can you finance a property bought at auction?
Yes, but auction purchases are harder to finance with a conventional mortgage because auction properties are typically sold as-is and lenders may restrict financing on them. Many buyers use short-term bridge loans or hard money loans to cover the purchase and close within the auction's deadline, then refinance or sell the property later. Because financing requirements and auction rules vary, review the terms of the sale and speak with a lender before you bid.
How quickly do you have to pay for a property after an auction?
Payment deadlines vary by auction and by county or sale venue, so read the terms of sale before bidding. Many auctions require a deposit on the day of the sale and the balance within a short window, sometimes within days or a few weeks. Because the deadline may be shorter than a conventional mortgage closing, lining up funds in advance through pre-approval or a short-term loan is critical to avoid losing your deposit.
Can you use a mortgage to buy a house at auction?
A conventional mortgage can sometimes be used, but it is not always practical. Lenders often require an appraisal, a clear title, and a closing timeline that auctions rarely allow, and some properties are sold without the inspections a mortgage lender would normally want. Before bidding, ask a lender whether it will finance the specific property type and whether its timeline fits the auction's payment deadline.

What next
Ready to do something with this?
Apply for financing in a few minutes, or join Biscayne Broker and put deals like this in front of lenders yourself.
General information, not legal, tax or financial advice. Loan terms come only from a lender, in writing, after underwriting. Licensing and compliance rules differ by loan type and state.