comparison
Fix and Flip Loans with No Income Verification
Editorial Team 15 min read
Table of Contents
- What Are Fix and Flip Loans with No Income Verification?
- Fix and Flip Loan Requirements Without Income Documentation
- Fix and Flip Loan Documents You'll Actually Need
- Stated Income Fix and Flip Loans Explained
- Fix and Flip Loan Closing Time and Funding Speed
- Loan Amounts, Interest Rates, and Total Costs
- Risks, Safeguards, and Borrower Suitability
- Frequently Asked Questions
Last Updated: October 18, 2026
What Are Fix and Flip Loans with No Income Verification?
Fix and flip loans with no income verification are short-term financing products for real estate investors who want to purchase and renovate properties quickly without submitting tax returns or W-2s.
Instead of asking "How much do you earn?", asset-based lenders ask "What's the property worth, and what will it be worth after renovation?"
These loans typically fund both the purchase price and renovation costs, and closing can happen in as little as 24 to 48 hours, which matters when you're competing with cash buyers or need proof of funds to lock in a contract.
Fix and Flip Loan Requirements Without Income Documentation
Asset-Based Underwriting Instead of Income
The core difference between fix and flip loans with no income verification and traditional mortgages is the underwriting approach.
Here is what a lender actually reviews when income documentation is off the table:
- As-is value and ARV. The lender orders an appraisal or broker price opinion to establish current market value, then reviews comparable sales to validate the ARV. A common pattern is to cap the loan at a percentage of ARV (often 65-75%) and a separate percentage of total project cost (often 70-90% LTC). The lower of the two results usually governs the loan amount.
- Renovation budget realism. The scope of work is checked line by line against typical costs in the market. Lenders frequently hold back a contingency reserve (commonly 10-15% of the rehab budget) and release it only as work is completed and inspected.
- Liquidity and reserves. Even without income verification, most lenders require 2-3 months of bank statements to confirm you can cover closing costs, carry costs, and a reserve. A common benchmark is enough liquid capital to cover 3-6 months of interest payments plus the down payment.
A worked example: contract a property at $200,000, budget $50,000 in renovations, and the appraiser supports a $300,000 ARV. At 70% of ARV the ceiling is $210,000; at 85% LTC on the $250,000 total project cost it's $212,500.
Many investors find this approach more transparent: you're not fighting income thresholds or debt-to-income ratios that penalize self-employment.
Credit Score and Credit Check Considerations
Most fix and flip lenders with no income verification still pull credit reports, though standards differ from traditional banks. A score of 620-650 is often acceptable versus 740+ for conventional lenders, and some lenders focus on recent payment history rather than overall score.
What matters more is whether you've defaulted on previous hard money or bridge loans, or have active collections.
If you've had credit challenges from business downturns or investment setbacks, be transparent about the context.
What Lenders Verify Instead of Income
Because income is not verified, lenders substitute other verification steps. Expect the following in a typical file:
- Identity and entity documents: government ID, LLC formation documents, operating agreement, and EIN.
- Property documents: purchase contract, appraisal or BPO, title commitment, and insurance binder.
- Project documents: itemized scope of work, contractor bids or licenses, permits where required, and draw schedule.
- Asset documents: bank and brokerage statements for the down payment and reserves, plus a proof-of-funds letter if a partner or private investor is contributing.
This document set explains why no-income-verification files move faster: the lender verifies assets and collateral, not IRS transcripts or employment calls.
Fix and Flip Loan Documents You'll Actually Need
Property and Renovation Documentation
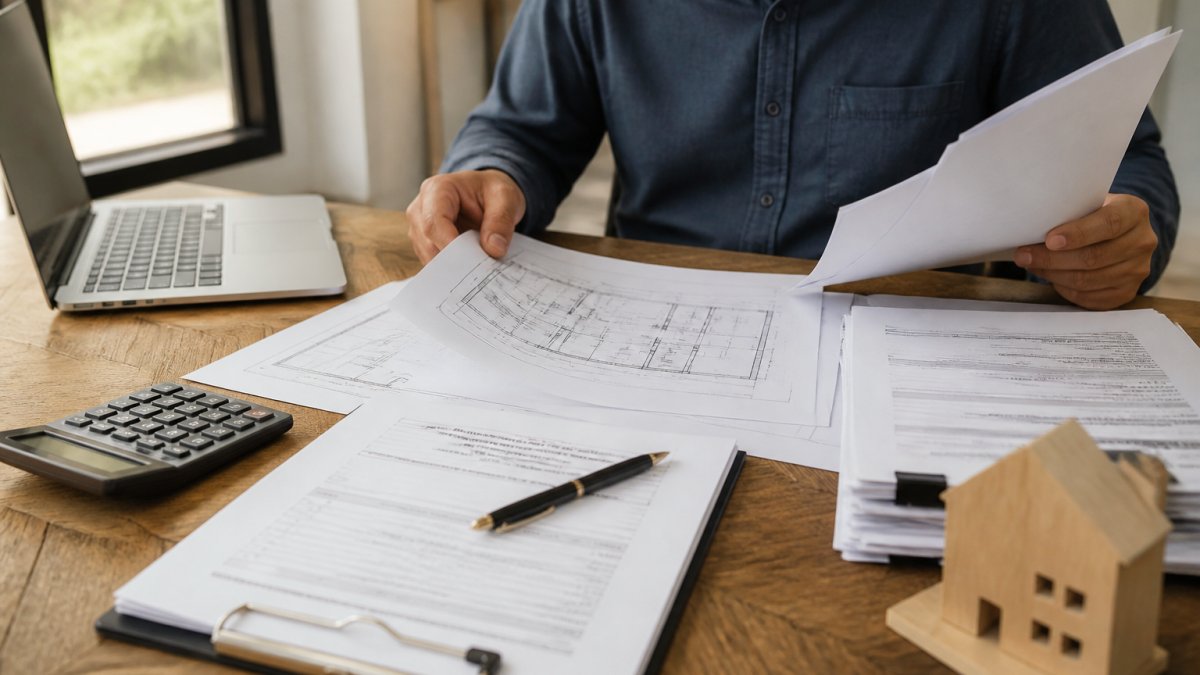
You'll need proof the property exists and that your renovation plan is realistic:
- Purchase contract or proof of the deal (signed contract showing purchase price)
- Property appraisal or broker price opinion (establishes current market value)
- After-repair value estimate (comparable sales showing post-renovation value)
- Scope of work or renovation estimate (detailed breakdown of planned improvements and costs)
The renovation estimate is critical, vague plans don't work. Lenders want line-item breakdowns (roofing $12,000, flooring $8,000, kitchen remodel $15,000, painting $3,000) so draws align with actual work completed.
Financial and Collateral Proof
Even without income verification, lenders want confidence you can handle the project and close. Bring:
- Bank statements (typically 2-3 months to show liquidity and closing cost reserves)
- Proof of funds (if using personal capital for down payment or closing costs)
- Previous fix-and-flip deals (if applicable, showing your track record and exits)
- Credit report (you'll authorize the lender to pull this)
Some lenders request a short explanation of your investment strategy or experience, especially for first-time flippers, just a way to confirm you're not a speculative amateur.
Stated Income Fix and Flip Loans Explained
A stated-income fix and flip loan is a specific category within no-income-verification lending: instead of submitting tax returns, you state your income on the application, and the lender relies on the property's value and your ability to complete the project rather than IRS records.
Stated-income loans work well for self-employed investors, business owners with variable income, or anyone whose tax returns don't reflect actual cash flow.
The trade-off is typically higher interest rates than fully-documented loans, but the speed and simplicity often justify the cost for time-sensitive deals.
Fix and Flip Loan Closing Time and Funding Speed
Speed is the primary advantage of fix and flip loans with no income verification. Traditional banks take 30-45 days minimum to close a mortgage. Hard money and bridge lenders operating through private capital can close in 5-21 business days, with some closing in as little as 24 to 48 hours.
The fast timeline is possible because underwriting is simplified: no employment verification, no employer calls, no underwriting committees. Asset-based decisions move quickly once the appraisal and renovation estimate are in place.
Closing speed matters when competing for deals. Sellers prefer cash offers or proof of funds, and a lender who can pre-qualify you and issue a commitment letter in 24 hours gives you credibility to make an offer knowing financing will close before the inspection period ends.
Loan Amounts, Interest Rates, and Total Costs
Loan-to-Value and Loan-to-Cost Ratios
Loan-to-value (LTV) and loan-to-cost (LTC) ratios determine how much a lender will advance relative to the property's value or your total project costs.
Loan-to-value compares the loan amount to the property's current appraised value: at 70-80% LTV on a $200,000 property, you can borrow $140,000-$160,000.
Loan-to-cost compares the loan amount to your total project costs (purchase + renovations). A lender offering 75% LTC on a $250,000 project will lend $187,500.
Interest Rates, Points, and Origination Fees
Interest rates on fix and flip loans with no income verification run higher than conventional mortgages and vary by loan size, property location, and experience.
Points (origination fees) are upfront costs expressed as a percentage of the loan: one point equals 1%, so a $200,000 loan with 2 points costs $4,000, often rolled into the balance or deducted from funding.
Total borrowing cost includes interest, points, appraisal fees, and title insurance.
A Worked Example of Total Borrowing Cost
Most lender pages quote a rate and points and stop there. What matters is the all-in cost to carry the loan from closing to payoff. Here's a realistic scenario with illustrative figures:
- Loan amount: $200,000
- Interest rate: 10% per year, interest-only
- Origination: 2 points ($4,000)
- Third-party costs: appraisal $600, title and closing $2,500, insurance binder $1,200
Extension fees are the cost most borrowers overlook. Before you sign, ask: What is the extension fee, how many extensions are allowed, and does the rate change at extension?
Payoff costs also matter. Those items belong in your profit-and-loss projection, not in a footnote.
How to Compare Offers Apples to Apples
When two lenders quote different rates and points, convert both to an all-in dollar cost for your expected hold period. A 9.5% loan with 3 points can be cheaper than a 10% loan with 1 point if you plan to hold only four months, and more expensive if you hold nine. Ask each lender for a written term sheet listing the rate, points, draw fee, extension terms, minimum interest, and any prepayment or exit fee.
Risks, Safeguards, and Borrower Suitability
Fix and flip loans with no income verification are powerful tools, but they carry real risks.
Market risk: If property values decline during your renovation, you could end up underwater.
Liquidity risk: These loans are short-term by design.
Safeguards to consider: Work with experienced contractors who've completed similar projects. Get multiple renovation estimates.
| Risk Factor | What It Means | How to Mitigate |
|---|---|---|
| Renovation overruns | Project costs exceed estimate, extending loan term | Build 10-15% contingency; use experienced contractors |
| Market decline | Property value drops during renovation | Verify comps; don't overestimate ARV; buy below market |
| Slow sale | Can't exit project on timeline, interest accrues | Have backup exit plan; price competitively; pre-market |
| Interest costs | High rates eat into profit margin | Calculate all-in cost before committing; target 20%+ profit |
| Liquidity crunch | Unexpected costs drain reserves | Maintain separate cash reserves; don't use 100% |
Fix and flip loans with no income verification remove traditional lending barriers, but they demand discipline and realistic planning.
The speed advantage is real, closing in 24 to 48 hours is possible when underwriting focuses on collateral rather than income documentation. Apply for pre-qualification early, get your property and renovation documentation organized, and work with a lender who communicates directly with you instead of hiding behind a credit committee. The Federal Reserve's guidance on alternative lending and NMLS licensing requirements for loan originators establish baseline standards for transparency and borrower protection across the industry.
Frequently Asked Questions
Can you get a fix and flip loan without income verification?
Yes. Many lenders offer fix and flip loans with no income verification, focusing instead on the property's after-repair value and your equity position. These loans are asset-based rather than income-based, meaning the lender underwrites primarily on the collateral, the property itself, and your ability to execute the renovation. Stated-income and no-doc fix and flip loans exist specifically for investors who cannot or prefer not to provide tax returns or W-2s.
What documents are typically required for a no-income-verification fix and flip loan?
Expect to provide proof of funds or liquidity, a purchase contract or property details, a rehabilitation budget with contractor quotes, a recent bank statement, and photo identification. Some lenders request a personal credit report even without income verification. Property appraisals or after-repair value estimates may be required to establish loan-to-value ratios. The exact list depends on the lender and loan amount, so confirm requirements early in the application process.
How quickly can a fix and flip loan close?
Fix and flip loans with no income verification can close in 24 to 48 hours with the right lender, though 5 to 21 business days is more typical depending on underwriting complexity and document completeness. Speed depends on how quickly you submit required paperwork and how straightforward your deal is. Lenders offering the fastest closing times often have streamlined underwriting and direct decision-making, avoiding committee delays.
What are stated income fix and flip loans, and how do they differ from other options?
A stated-income fix and flip loan allows you to state your income without providing tax returns or W-2s to verify it. The lender relies on your word and the property's fundamentals. This differs from a no-doc loan (which requires even fewer documents) and from traditional income-verified loans. Stated-income loans sit between full documentation and no-doc, offering flexibility for self-employed investors or those with irregular income on paper while still maintaining some borrower accountability.
What should I watch out for with no-income-verification fix and flip loans?
Rates and fees are typically higher than conventional mortgages because the lender assumes more risk without income verification. Loan-to-cost ratios may be lower, requiring larger down payments. Exit strategy matters, if the property doesn't appreciate as projected or the renovation costs balloon, you could face a shortfall. Verify that the lender actually delivers promised closing speeds and that no hidden fees emerge mid-application. Confirm state licensing and that the lender operates in your state.
FAQ
Can you get a fix and flip loan without income verification?
Yes. Many lenders offer fix and flip loans with no income verification, focusing instead on the property's after-repair value and your equity position. These loans are asset-based rather than income-based, meaning the lender underwrites primarily on the collateral—the property itself—and your ability to execute the renovation. Stated-income and no-doc fix and flip loans exist specifically for investors who cannot or prefer not to provide tax returns or W-2s.
What documents are typically required for a no-income-verification fix and flip loan?
Expect to provide proof of funds or liquidity, a purchase contract or property details, a rehabilitation budget with contractor quotes, a recent bank statement, and photo identification. Some lenders request a personal credit report even without income verification. Property appraisals or after-repair value estimates may be required to establish loan-to-value ratios. The exact list depends on the lender and loan amount, so confirm requirements early in the application process.
How quickly can a fix and flip loan close?
Fix and flip loans with no income verification can close in 24 to 48 hours with the right lender, though 5 to 21 business days is more typical depending on underwriting complexity and document completeness. Speed depends on how quickly you submit required paperwork and how straightforward your deal is. Lenders offering the fastest closing times often have streamlined underwriting and direct decision-making, avoiding committee delays.
What are stated income fix and flip loans, and how do they differ from other options?
A stated-income fix and flip loan allows you to state your income without providing tax returns or W-2s to verify it. The lender relies on your word and the property's fundamentals. This differs from a no-doc loan (which requires even fewer documents) and from traditional income-verified loans. Stated-income loans sit between full documentation and no-doc, offering flexibility for self-employed investors or those with irregular income on paper while still maintaining some borrower accountability.
What should I watch out for with no-income-verification fix and flip loans?
Rates and fees are typically higher than conventional mortgages because the lender assumes more risk without income verification. Loan-to-cost ratios may be lower, requiring larger down payments. Exit strategy matters—if the property doesn't appreciate as projected or the renovation costs balloon, you could face a shortfall. Verify that the lender actually delivers promised closing speeds and that no hidden fees emerge mid-application. Confirm state licensing and that the lender operates in your state.
What next
Ready to do something with this?
Apply for financing in a few minutes, or join Biscayne Broker and put deals like this in front of lenders yourself.
General information, not legal, tax or financial advice. Loan terms come only from a lender, in writing, after underwriting. Licensing and compliance rules differ by loan type and state.